Payday. $1,000 has just landed in your account, and before anything else gets its sticky fingers on it, you open your bank app and a blank note on your phone.
You've been here before, though. Last time it was twelve neat categories in a shiny new spreadsheet, and a smug little glow on Sunday night. By the second week a birthday present, a higher bill and a school trip had gobbled up three of them, and the spreadsheet got closed for good.
So this time, let's make a simple budget with no categories and no calendar month. Your money arrives on paydays and goes out on real things, so it starts today, on payday, and follows this pay all the way to the next. If you're new to budgeting, or you've started a few and stopped, it's a good place to begin.
Payday morning: what's come in, what's due, what's left
Use the pay cycle you really have, whether that's weekly or twice a month. Get the dates and amounts from the bank app, not from memory (memory is a hopeless optimist and rounds everything down).
Write down what came into your account. Then peek ahead to your next payday and write down everything that has to come out before then. For example, say the rent share, the phone and the car payment are all due, and together they come to $600. Take that from the $1,000, and you've got $400 to live on until next pay.
If something big is lurking, like a car insurance bill next month, write it next to the pay it'll come out of.
And if your pay wobbles from one payday to the next, plan with the smaller of your last two. Then when a bigger one turns up, the extra feels a bit like finding money in last winter's coat pocket.
Don't worry about getting these numbers perfect. If a bill's amount is a total mystery, pop it down with a question mark and make finding the real figure your first little job this pay. It's so much better to find out now, while there's still time to make room for it.
Still payday: the things you'd hate to run short on
Now look at that $400 and pick the three things you'd really hate to run short on. For you it might be the vet, a little emergency fund for surprises, or a night out with a friend once a month.
Give those three their money first, say $100 across all three, and the other $300 covers groceries and everything else until next pay.
What most budgets start with
A list of categories somebody else picked for you, lined up neatly to keep a spreadsheet happy.
What I'd start with
Your pay, your bills and the three things that matter most to you right now. That's the whole list, and every line on it is yours.
Your three will be different from anyone else's, and there's no right list. I'd bet you could rattle yours off faster than you could name twelve categories, couldn't you?
If the $400 won't stretch to all of it, shrink one of the three for this pay, and be clear with yourself which one. It feels a bit wobbly the first time. But you'll feel so much better choosing than running short on the thing you cared about most.
Halfway to next pay: one quick budget check
Somewhere around the middle of the pay, open the app once (just once!) and check how much of the $300 is left. You're looking for anything that's being spent faster than you expected, like the groceries.
If the groceries are running ahead, at least you've spotted it on a Wednesday, and you can borrow a little from one of your three to cover it. That's so much easier than finding out the day before payday, staring into a fridge with one lonely lemon in it.
And if everything looks about right, close the app and get on with your evening.
The day before next pay: what surprised you
Your first plan will be wrong in a few places, and that's ok. For example, say you planned $80 for groceries and it came to $100. Write $100 in for next pay, and your plan is already a lot closer to your real life.
Before your next pay lands in your account, sit down with your note for a few minutes and answer three questions.
- What was close?Leave those lines alone.
- What surprised me?Write the real amount in for next pay.
- What is the one line I'll change?Pick one, and leave the rest for another pay.
Then give it three paydays before you decide whether it works, even if the first one makes you want to fling your phone across the room. HOLD YOUR NERVE! Each round you fix one or two numbers, and by the third payday there won't be many surprises left.
Next payday: quicker the second time
Your new pay lands in your account, and you do the same three numbers again from the top. It's quicker the second time, because the bills are already sitting in your note waiting for you.
Once your first simple budget is done, these posts pick up where this one leaves off:
- A cushion for surprises. How to start an emergency fund from nothing.
- Room for fun without the midnight cart frenzy. How to stop impulse spending without feeling deprived.
- A monthly look back. A 15-minute money date is a nice moment to see how your plan went.
For your next payday
Set a reminder for the morning your next pay arrives. When it goes off, open your bank app and write three numbers on a note: what came in, what's due before the next pay, and what's left.
Did this pay go sideways?
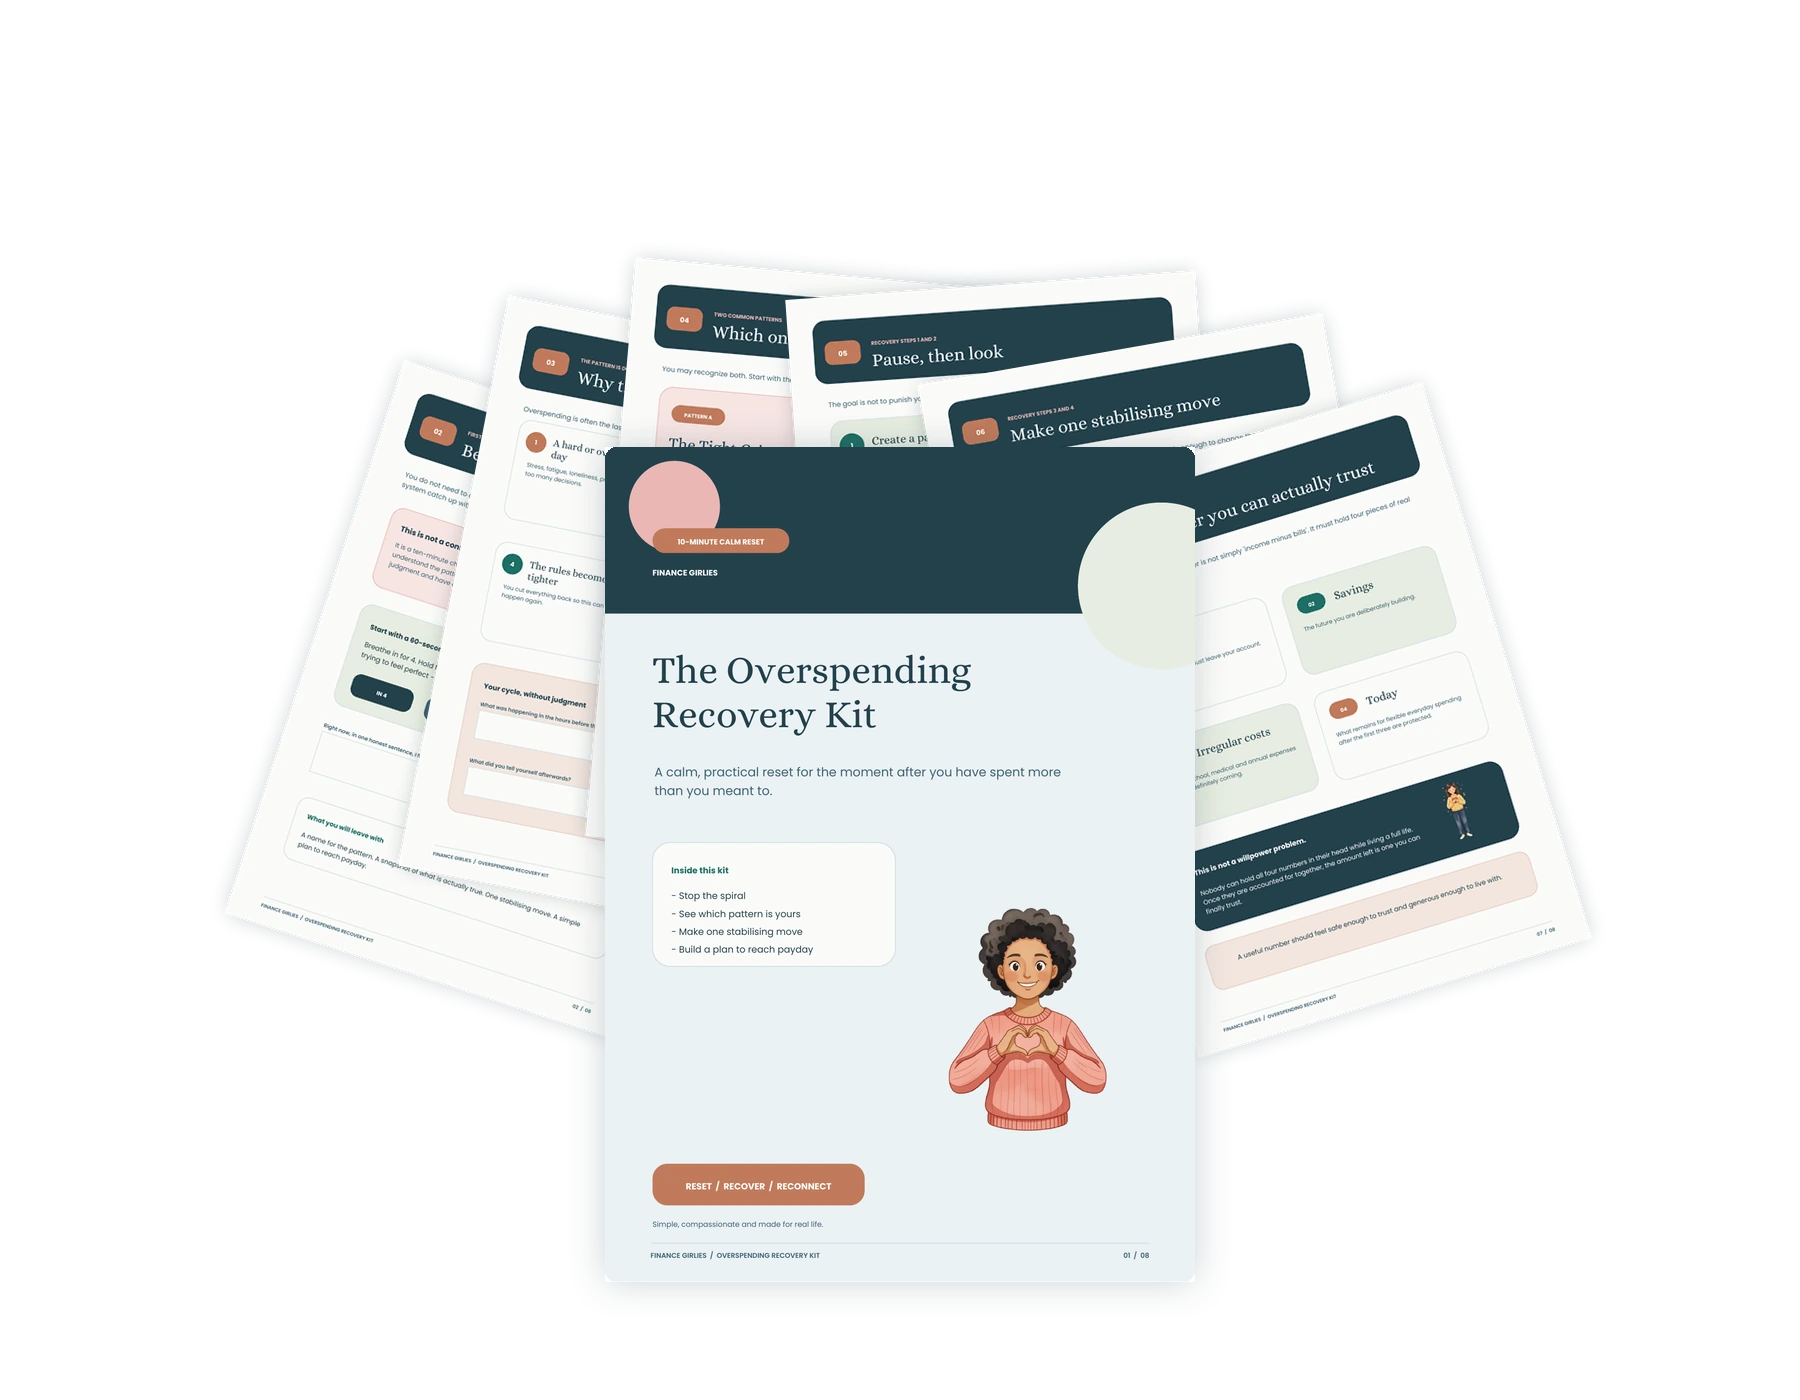
The free Overspending Recovery Kit is for the pay that wobbled. It starts with one page for your balance, the bills due before your next payday and one thing to do about it, and it takes about ten minutes.
Get the free kitFree. Eight pages, on screen or printed.And when your next pay lands in your account and those three numbers come together in no time, pour yourself something nice and enjoy that feeling, lovely. You made that happen.
This is general education only, not financial, tax or legal advice.
3 Comments
Comments are closed.